The pension stopped. The health insurance canceled. The forms arrived without instructions.
When an Illinois teacher dies — whether still in the classroom or years into retirement — TRS in Springfield does not call the family. It freezes the pension. It sends a claims packet. And it waits.
Meanwhile, the Comptroller's ACH recall pulls back any direct deposit for a month after the death. The bank may freeze the joint account until the reversal clears. TRIP or TRAIL health coverage cancels retroactively to midnight on the date of death. And the forms that arrive from TRS use statutory language that assumes the reader already knows whether they are a "dependent beneficiary" or a "nondependent beneficiary" — a distinction that determines whether a monthly annuity is even possible.
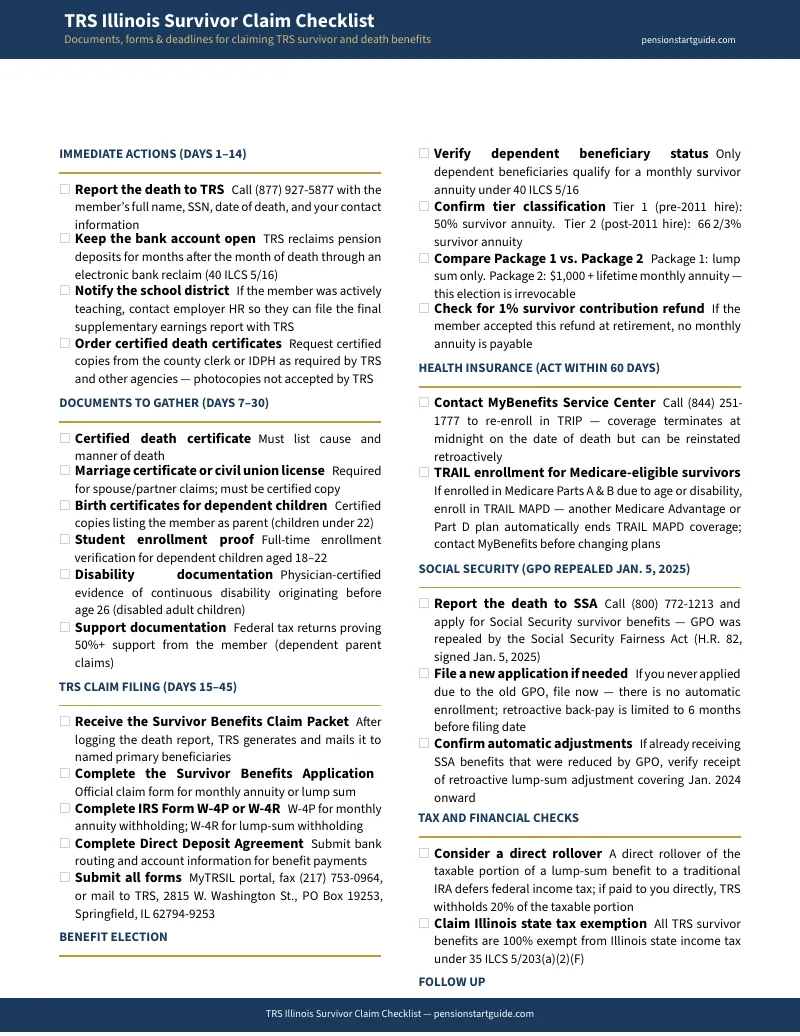
The free checklist tells you what to gather. The full guide is the TRS Illinois Survivor Claim System — the step-by-step sequence that puts every form, deadline, and agency call in the order your family actually needs them.
What the guide covers that free resources don't
TRS publishes the pension code. The union reprints it. Financial advisors use it to pitch rollover annuities. None of them publish a neutral procedural workflow that connects TRS, CMS, and the Social Security Administration into one claim sequence.
- Active-member vs. retiree death benefits, untangled — the salary-based lump sum (up to four years' highest salary) that only applies when an active teacher dies, the fixed $1,000 annuitant death benefit, and the accumulated-contribution refund that may or may not exist depending on how long the retiree drew a pension
- Tier 1 and Tier 2 survivor annuity rules, side by side — 50% of earned annuity for Tier 1 versus 66.67% for Tier 2, with the final average salary windows, pensionable salary caps, COLA formulas, and minimum floors ($400/$600) that determine what the annuity actually pays in practice
- TRIP and TRAIL health reinstatement steps — the retroactive midnight cancellation, the re-enrollment path for survivors receiving a monthly annuity, the CMS MyBenefits workflow, and the Medicare Beneficiary Identifier requirement that silently terminates coverage if it is not filed
- Social Security after the GPO repeal — the Government Pension Offset was repealed in January 2025; surviving spouses who were previously denied or reduced are now eligible for full Social Security survivor benefits, and the guide walks through Form SSA-10 and the six-month retroactive back-pay limit on new claims
- Tax treatment decoded — the 100% Illinois state income tax exemption, the federal 1099-R breakdown (Box 2a versus Box 5), and the direct rollover that avoids mandatory 20% federal withholding on lump sums
- Reversionary annuity provisions — the extra monthly payment for survivors of retirees who elected an irrevocable reduced pension, how it stacks on top of the standard survivor benefit, and the rules if the designated beneficiary predeceased the retiree
- QILDRO and divorce complications — how a Qualified Illinois Domestic Relations Order divides benefits, and the automatic disqualification of a former spouse named on a pre-divorce beneficiary form
- Claim processing timeline — realistic 4-to-8-week processing expectations, what causes delays, and how to track claim status with TRS
Who this is for
- Surviving spouses and civil union partners who need to know whether a monthly annuity, a lump-sum benefit, or a contribution refund applies — and whether the answer changes under Tier 1 versus Tier 2
- Adult children managing a parent's claim from across the state or across the country, coordinating TRS, CMS MyBenefits, and the Social Security Administration without a road map
- Named non-spouse beneficiaries who received a claims packet and discovered they are legally ineligible for a monthly annuity — and need to understand the lump-sum refund, the tax rollover, and the 20% withholding trap
- Estate executors determining whether TRS benefits pass outside probate to a designated beneficiary or fall into the estate and require Letters of Office or a Small Estate Affidavit
Why the free checklist isn't enough
The checklist covers the first 72 hours: who to call, what documents to gather, how to handle the direct deposit clawback. It is designed to stop the panic and get the paperwork started.
But the checklist cannot explain why a nondependent beneficiary is ineligible for a monthly annuity. It cannot walk through the Tier 1 versus Tier 2 COLA calculation that determines whether a survivor's income keeps pace with inflation or falls behind. It cannot map the TRIP health reinstatement workflow or the Social Security filing process that became available after the GPO repeal. Those require the full guide.
What this is not
This guide is not financial, legal, or tax advice. It does not recommend which benefit option to choose, which rollover vehicle to use, or whether to hire an attorney. It explains the TRS claim process — every form, every deadline, every agency — and the trade-offs of each decision. The choice stays with the family.
Pension Start Guide is not affiliated with the Teachers' Retirement System of the State of Illinois, the Department of Central Management Services, the Illinois Education Association, or any government entity.
Full refund, no time limit
If the guide does not help your family navigate the claim process, email [email protected] for a full refund. No time limit, no questions.
Your family is already dealing with enough. The claim process shouldn't be another thing to figure out alone.
Get the TRS Illinois Survivor Benefits Guide →
The free checklist is available on the same page — no purchase required.