When an Ohio educator dies, the family shouldn't have to decode a pension handbook to keep the bills paid
Your spouse or parent taught in Ohio for years — maybe decades. They earned a pension through STRS Ohio. And now that they've died, you're the one sitting at the kitchen table with a stack of paperwork, trying to figure out which benefits continue, which ones you have to apply for, and which deadlines you can't afford to miss.
STRS Ohio's own materials are written for actuaries and legislators. They define terms but don't tell you what to do first, what to do next, or how one decision affects the rest. You're left calling Member Services, waiting on hold, and still not sure whether you asked the right questions.
Meanwhile, the financial advisors who show up with "free consultations" have their own agenda — they want to roll your lump sum into a fee-based account, not help you understand what STRS Ohio already provides.
The Survivor Claim Navigator: Every Step, Every Form, Every Deadline — In Order
The STRS Ohio Survivor Benefits Guide is a plain-language operational manual that puts every survivor decision in sequence. It doesn't sell financial products or tell you which option to choose. It explains what each option does, how the math works, and what to ask — so the choice stays with you.
The guide follows your specific path. An active teacher's death triggers different rules than a retiree's death. A Defined Benefit member's family faces different choices than a Defined Contribution family. The guide routes you to exactly the sections that apply, so you're not reading 40 pages of rules that don't affect you.
What's Inside
- Death reporting protocol — who to call at STRS Ohio, what information they need, and how to prevent direct-deposit complications while your claim processes. Most families don't know that a retiree's final month payment can trigger a bank reversal if the timing is wrong.
- Active-member survivor benefit calculations (ORC 3307.66) — the three formulas STRS Ohio uses to calculate qualified survivor benefits (dependent-based, service-based, and retirement-based), laid out so you can see which one STRS will select and roughly what it means in monthly dollars.
- Retiree Plan of Payment breakdown — what actually continues under Plan I, Plan II (Options 1–4, with and without reversion), and Plan III (Annuity Certain). If your spouse chose Plan I, the guide explains exactly what you're entitled to and what you're not — before STRS Ohio's letter arrives.
- Lump-sum versus monthly annuity comparison — the account refund formula (accumulated contributions + compound interest + 50% statutory match), the tax hit, and the trade-offs. This is the decision financial advisors push hardest on, and the one where neutral information matters most.
- Health care continuation rules — the service-credit thresholds (15 years for pre-August 2023 retirees, 20 years for post-August 2023), enrollment requirements, and the dental/vision contract periods. One missed enrollment window can mean permanent loss of coverage.
- Social Security after the GPO/WEP repeal — the Government Pension Offset and Windfall Elimination Provision were repealed in January 2025 (retroactive to January 2024). If your spouse was previously told their Social Security survivor benefit would be reduced or eliminated because of the STRS pension, that's no longer true. The guide covers the steps to claim your full, unreduced benefit and what retroactive adjustments to expect.
- Form 1099-R and tax navigation — which portions of survivor payments are taxable, how the mandatory 20% federal withholding applies to lump sums, the 60-day rollover window, and Ohio's state income tax treatment.
- Divorce, DOPOs, and competing claims — how a Division of Property Order filed under ORC 3307.60 affects what the current spouse receives, and how competing beneficiary designations are resolved.
- DC and Combined Plan survivor rules — the different (and more limited) options when the member participated in the Defined Contribution or Combined Plan.
- 5 printable worksheets — a survivor claim tracker, document inventory checklist, benefit comparison worksheet, agency communication log, and health care enrollment deadline tracker — each a standalone PDF you can print and fill in.
Who This Guide Is For
- Surviving spouses who need to know what continues automatically, what requires a claim, and what decisions they face in the first 90 days
- Adult children helping a surviving parent navigate the paperwork — especially when the parent is overwhelmed and the clock is running
- Named beneficiaries (non-spouse) who received a letter from STRS Ohio and aren't sure whether they're entitled to monthly payments or a one-time lump sum
- Estate executors who need to know which STRS benefits pass outside probate and which ones require estate accounting
Why Not Just Use the Free Information?
STRS Ohio's website defines terms and publishes forms. It does not tell you what to do first, what depends on what, or how one decision (taking the lump sum) permanently closes the door on another (monthly survivor benefits).
Union and retiree association websites focus on advocacy — COLA restoration, board reform, investment returns. They publish almost nothing on the step-by-step mechanics of filing a survivor claim.
Financial advisor content is designed to capture assets. The "free retirement review" is a sales funnel, not a neutral guide. They explain the options that lead to a rollover and skip the ones that don't generate a fee.
And the majority of third-party articles online still describe the Government Pension Offset as active law — warning families that their Social Security survivor benefits will be reduced by two-thirds. That provision was repealed in January 2025. Families who trust that outdated information may never file for benefits they're legally entitled to.
This guide is independent. It doesn't sell financial products, doesn't recommend a specific option, and doesn't take a commission. It puts every step in order and explains the trade-offs so you can make the decision with your own advisors.
Satisfaction Guarantee
If the guide doesn't help you, email [email protected] for a full refund — no time limit, no questions.
Get Started
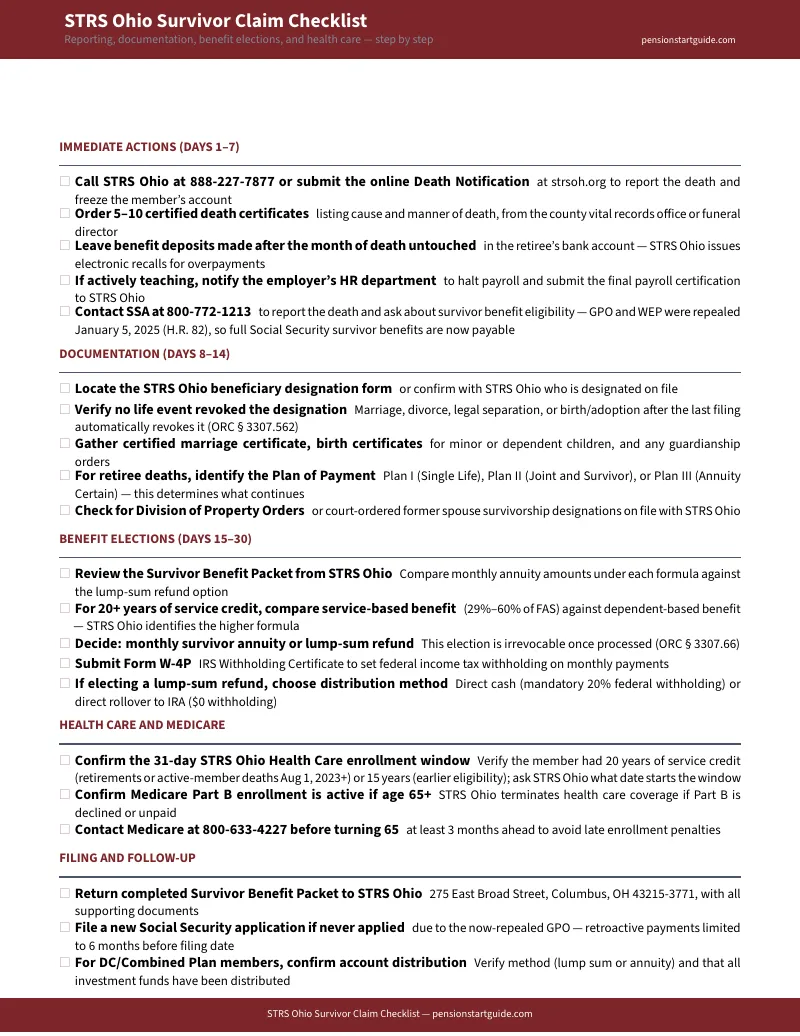
Download the free STRS Ohio Survivor Claim Checklist to see the documents and deadlines for the first 30 days. When you're ready for the full claim sequence — every benefit formula, every plan of payment, health care continuation, Social Security coordination, tax paperwork, and the worksheets to organize it all — the complete guide is .