Your benefit option election is irrevocable — and the handbook won't help you compare them
When you file Form RET-54, you pick a benefit option that determines your monthly pension for life. Maximum pays the most but leaves your spouse with nothing. Joint-and-Survivor protects them but permanently reduces your check. Pop-Up gives you a middle road — if the math works. And once the 30-day post-retirement window closes, the election is final.
The official NYSTRS handbook covers all six membership tiers in a single dense document and presents the options without comparison. Your union rep can explain the broad strokes but is restricted from auditing your specific numbers. Your financial advisor may still be working from pre-2024 rules — quoting a five-year FAS for Tier 6 and an unreduced age of 63 that no longer applies with 30 years of service.
The Retirement Filing System: every step, every form, every deadline in the order you need them
The NYSTRS Retirement Guide is built around the Retirement Filing System — a chronological process framework that takes you from "I think I'm eligible" through your first pension payment. Instead of hunting through a 200-page handbook for the rules that apply to your tier, you work through the steps in sequence: verify your tier, audit your FAS, compare your benefit options with real trade-off analysis, file Form RET-54, and navigate the 30-day post-retirement modification window.
Every chapter targets a specific decision point. You never get generic "here are the rules" — you get "here is what this rule means for your monthly check and what to ask your NYSTRS representative before you sign."
What's inside the guide
- Tier architecture decoded — because Tier 4's "30 and 55" rule, Tier 5's steeper reductions, and Tier 6's new age-58 unreduced threshold all change the math differently, and you need the rules for your tier isolated from the other five
- FAS calculation with worked examples — showing exactly how the 10% salary cap excludes excess earnings, what counts as reportable salary versus excluded stipends, and how to audit the number NYSTRS gives you on your Benefit Profile
- Benefit option comparison framework — Maximum, Joint-and-Survivor (100/75/50/25%), Pop-Up Survivor, Guarantee (5-year and 10-year), and Lump Sum Annuity Reserve, each with the trade-offs mapped: monthly payout impact, beneficiary coverage, what happens if your beneficiary dies first, and whether the Pop-Up restores your full amount
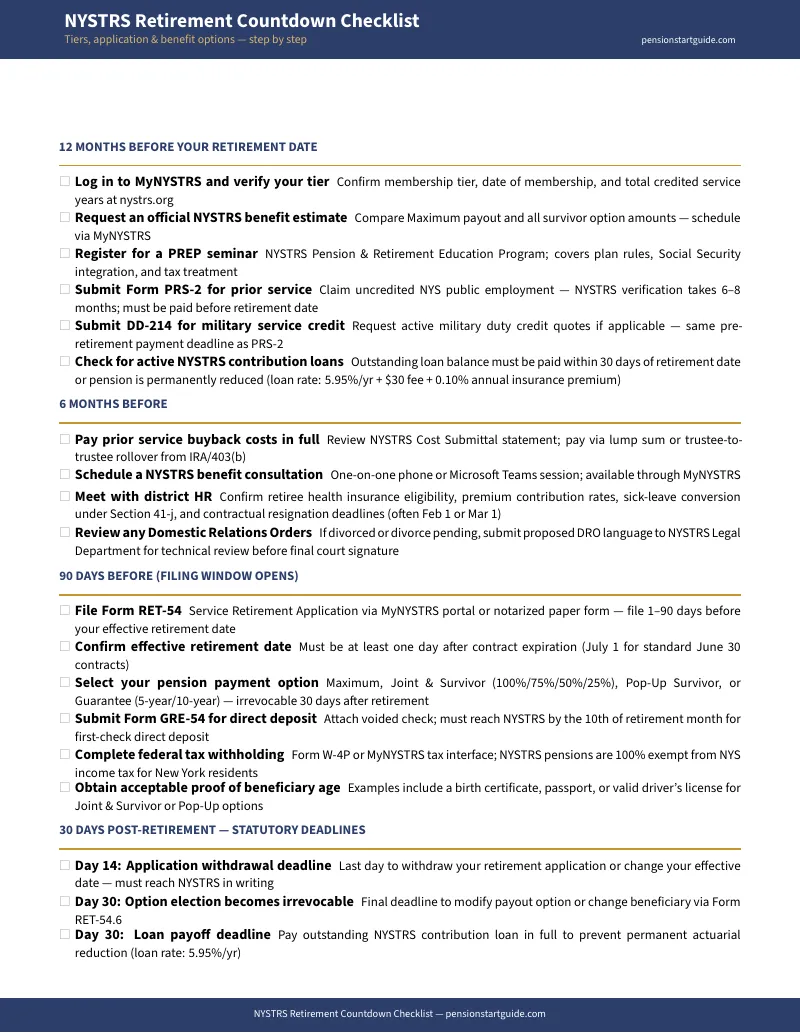
- Form RET-54 line-by-line walkthrough — filing through MyNYSTRS online or by mail, direct deposit setup (Form GRE-54), tax withholding (W-4P), and the exact 1-to-90-day pre-retirement filing window with delivery rules
- Service credit purchase deadlines — how to buy back prior public service, substitute teaching, and military time before your retirement date, with cost formulas by tier and the penalty for missing the cutoff (forfeiture, permanently)
- District health insurance coordination — bridging the gap between NYSTRS pension deductions and your district's actual health coverage rules, NYSHIP enrollment, Medicare Part B reimbursement, and Section 41-j sick-leave conversion credit
- Post-retirement earnings, DROs, and legal orders — the Majauskas formula for divorce-related benefit division, the Section 212 waiver through June 30, 2027, bona fide termination requirements, and Power of Attorney rules
- 5 printable worksheets — retirement countdown timeline, benefit option comparison worksheet, service credit audit checklist, district coordination checklist, and agency communication log — each designed to fill in and bring to your NYSTRS consultation or district HR meeting
Updated for 2026 legislative changes
The guide reflects three statutory reforms that most planning tools and advisor blogs still miss:
- Tier 6 FAS reform (Chapter 56, Laws of 2024) — the Final Average Salary formula for Tier 6 is now the highest three consecutive school years, matching Tier 4, not the old five-year average
- Tier 6 unreduced age (Chapter 58, Laws of 2026) — Tier 6 members with 30+ years of credited service can retire at age 58 without age reductions, down from 63
- WEP and GPO repeal (Social Security Fairness Act, 2025) — both federal provisions are repealed for benefits payable from January 2024; the separate Tier 3 Article 14 plan-level offset is not affected
Who this guide is for
- Tier 4 career teachers approaching the "30 and 55" unreduced threshold or age 62, weighing Maximum against survivor coverage
- Tier 6 educators evaluating the new age-58 rule and the updated three-year FAS formula after the 2024 and 2026 reforms
- School administrators, principals, and SUNY/community college faculty who elected NYSTRS over ORP and need to understand how administrative stipends and FAS caps interact
- Teachers completing a service credit purchase — prior public service, military, or substitute teaching — before their retirement date
- Members with a Domestic Relations Order who need to know how the Majauskas formula restricts their option election
Why not just use the free resources?
The official NYSTRS handbook is comprehensive — it covers every tier, every edge case, every statutory provision. That is also its limitation. When you are 90 days from retirement and need to know whether your FAS calculation under the new three-year rule uses July-to-June school years or calendar years, you do not want to read about Tier 1 vesting rules from 1973.
Union workshops and PREP seminars deliver excellent high-level overviews, but they run 60 to 90 minutes for a room of 200 people. They cannot audit your specific Benefit Profile, tell you whether the Pop-Up or Joint-and-Survivor option makes more sense for your household, or walk you through what happens if your beneficiary predeceases you under a non-pop-up election.
Financial advisors who specialize in teacher retirement can personalize their advice — but many are also selling 403(b) annuities or IRA rollovers, and their process guidance frequently lags the most recent statutory changes.
This guide fills the gap between "here are the rules" and "here is how to apply them to your situation." It is an independent process reference with no financial products to sell, no annuities to pitch, and no recommendation on which option to choose.
Satisfaction guarantee
If the guide does not help you navigate your NYSTRS retirement process, email [email protected] for a full refund — no time limit, no questions asked.
Start your retirement filing process
Download the free NYSTRS Retirement Countdown Checklist to see the timeline — what to verify, file, and coordinate at each stage. When you are ready for the full walkthrough with worked examples, option comparison frameworks, and line-by-line form instructions, the complete guide is waiting for you at .