You get one chance to choose your TSERS payment option. It's permanent. And the official handbook won't tell you which trade-offs matter for your household.
North Carolina teachers, state employees, and UNC system staff retire under one of the most complex state pension structures in the country. TSERS gives you six payment options — Maximum Allowance, two Joint & Survivor levels, Social Security Leveling, and two Pop-Up variants — and once you submit your election through ORBIT, you cannot change it. Not after a year. Not after a divorce. Not ever, unless you return to active TSERS service for at least three more years.
The official TSERS handbook covers all of this. It covers every hire-date tier, every exception, every rule. That's the problem. A teacher hired in 2012 opens the handbook and reads health-plan rules written for someone hired in 2004. A state agency worker at 29 years and 8 months of service can't tell whether her sick leave bank pushes her past 30. A married couple trying to decide between Option 2 and Option 6-2 finds the math but not the question they actually need to answer.
The TSERS Retirement Sequence — one member's path through the process, start to finish
This guide does what a handbook cannot: it follows one retirement from the first benefit estimate through the first monthly deposit, in order, with the trade-offs for each decision explained side by side. Not every member's rules. Yours.
What's inside
Your benefit formula, line by line
Average Final Compensation, the 1.82% accrual factor, creditable service — the three inputs that determine your Maximum Allowance. The guide shows you how to verify each one in ORBIT and catch the errors that drag your benefit down before they become permanent.
Service record audit and sick leave conversion
Your MARS statement in ORBIT is the foundation of your benefit calculation. The guide walks through how to read it, what discrepancies to look for, and how unused sick leave converts to creditable service under the 20-day rule — including the hard limits on what sick leave can and cannot do for your vesting or health-plan eligibility.
All six payment options compared — not listed, compared
Maximum Allowance pays the most per month but stops the day you die. Option 2 continues your full check to a surviving spouse but permanently reduces what you both receive while you're alive. Option 4 inflates your check before 62 and cuts it after — with zero survivor protection. The Pop-Up options offer a middle path. The guide lays out the trade-offs for each, including the questions to bring to your retirement counselor before you commit.
The ORBIT application, step by step
The 120-day filing window, ID.me setup, document uploads, and what to do if your employer's Form 641 is late. The guide follows ORBIT Steps 1, 2, and 3 in sequence so you know what each screen asks for and what triggers a hold on your application.
Service credit purchases — the deadline that cannot move
Military service, withdrawn service, out-of-state public service — if you want the extra credit in your benefit, every dollar must be paid before your effective retirement date. The guide covers what's purchasable, how to get a cost estimate, and the pre-tax funding options through your NC 401(k) or NC 457.
Contributory Death Benefit election
A $10,000 benefit paid to your beneficiary if you die as a retiree. You have 60 days after your retirement effective date to elect it, and the monthly premium is deducted from your pension check. The guide explains the election window, the cost, and how it interacts with your payment option's survivor provisions.
State Health Plan transition
If you were hired before October 2006, you get fully employer-paid retiree coverage after five years. Hired between 2006 and 2020? Your coverage tier depends on whether you hit 20 years, 10 years, or fell short. Hired after January 1, 2021? You are statutorily barred from retiree medical coverage under the State Health Plan. The guide maps your hire-date tier to your coverage, explains dependent premium costs, and walks through Medicare coordination at 65.
Return-to-work rules and the 6-month separation
Work for any TSERS-participating employer during your first six months of retirement — even as a substitute, even part-time — and TSERS can retroactively cancel your retirement and demand full repayment of every check you've received. The guide covers the separation rule, the annual earning cap, and the conditions that trigger cancellation.
WEP and GPO — what the repeal actually means for TSERS members
The Social Security Fairness Act, signed January 5, 2025, repealed both provisions. TSERS members pay Social Security taxes, so standard TSERS pensions were rarely affected by WEP. The guide clears up the confusion between the federal repeal and TSERS Option 4's leveling reduction, which is a plan-level calculation and remains unchanged.
Who this guide is for
- NC teachers and school staff within one to two years of retirement who need to confirm their service, model their benefit, and prepare for the ORBIT application
- State agency and UNC system employees evaluating payment options and health-plan eligibility based on their specific hire date
- Spouses and household partners involved in the survivor-protection decision who want to see the lifetime income trade-offs in plain language
- Members considering a service purchase who need to understand the cost basis, the payment deadline, and the pre-tax funding options
Why the free checklist isn't enough
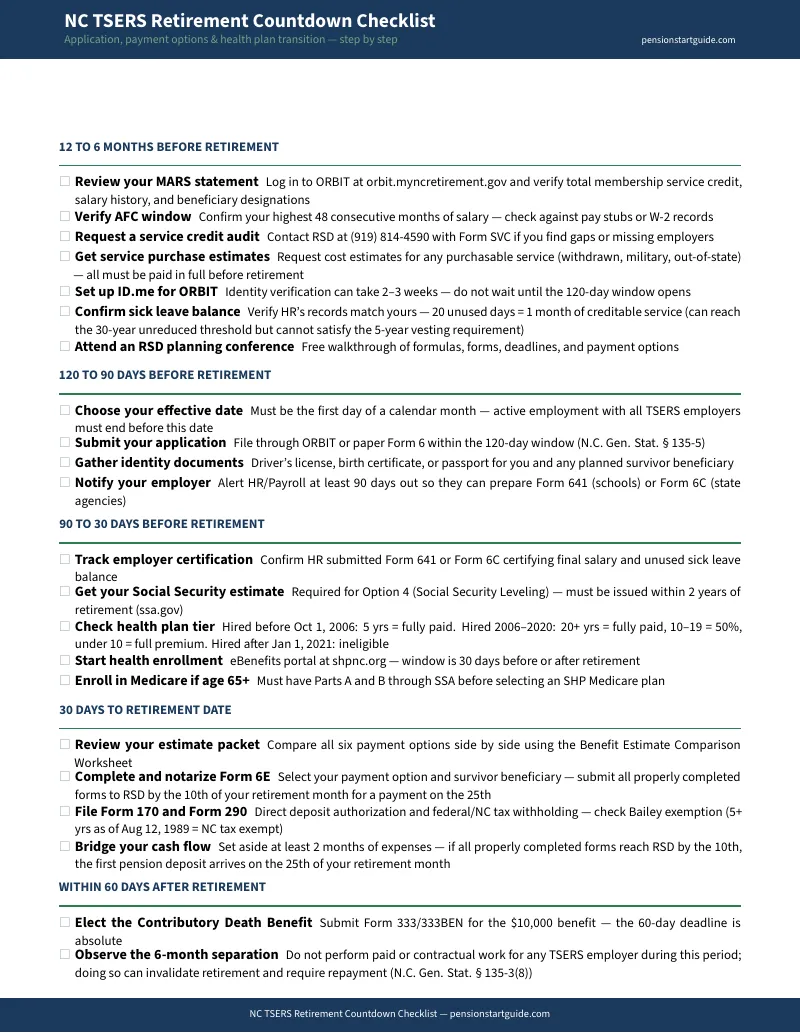
The free NC TSERS Retirement Countdown Checklist gives you the steps in order — what to do 12 months out, 6 months out, 120 days before filing. It's a solid starting line. But the checklist tells you what to do. It doesn't tell you how to evaluate the trade-offs in each decision.
The difference between Option 2 and Option 6-2 isn't a checklist item. It's a question about your spouse's independent income, your household's tolerance for a permanently reduced check, and whether the pop-up feature is worth the additional monthly cost. The full guide puts those questions in front of you with the numbers side by side — before you're sitting in ORBIT with a submit button and no undo.
Full refund, no time limit
If the guide doesn't help you, email [email protected] for a full refund. No time limit. No forms. No questions.
The checklist is free — download it and start your timeline today. When you're ready to work through the payment-option trade-offs and the ORBIT application, the full guide is here.