You Got Your PSRS-151 Estimate — Now You're Staring at Five Options and No Way to Compare Them
PSERS prints the numbers. It does not explain the trade-offs. The Maximum Single Life Annuity gives you the highest monthly check — but if you die the day after your first payment, your spouse gets nothing beyond a refund of leftover contributions. Option 2 guarantees your spouse a lifetime pension at the same monthly amount — but that monthly amount is permanently lower, even if your spouse predeceases you. Option 4 lets you withdraw your accumulated contributions and interest as a lump sum — but every dollar you take out permanently reduces your monthly check for life. The exit counseling slides present all five options in a grid. Nobody puts them side by side with worked dollar examples for your membership class.
Meanwhile, seven membership classes use four different multipliers and two different salary-averaging periods. A Class T-D teacher with the 2.5% multiplier reads the same handbook as a Class T-G hybrid member with 1.25%. The superannuation rules that let a T-C member leave with 30 years of service at any age do not exist for T-E. Confusing the two means planning around a retirement date that doesn't apply to your class.
The PSERS Retirement Filing Sequence — Every Step, in Order, for Your Membership Class
The Pennsylvania PSERS Retirement Guide is a step-by-step filing sequence that follows one member's path from the first estimate request through the first pension payment. It identifies your membership class, walks through the Application for Retirement (Form PSRS-8), lays every payout option side by side with worked examples, and explains the health-benefit and service-credit decisions that have hard deadlines you cannot extend. It never recommends an option — it explains what each one does, what it gives up, and what questions to bring to exit counseling.
What's Inside
- Membership class identification — Classes T-C, T-D, T-E, T-F, T-G, T-H, and DC, each class's multiplier (1.0% to 2.5%), Final Average Salary window (3-year vs. 5-year), and the exact superannuation eligibility rules that apply to your class alone
- Service credit audit and purchases — how credited service accrues under PSERS, which types you can purchase (out-of-state public school teaching, military service, approved leaves of absence), and the hard rule that every purchase must be completed before your effective date of retirement
- All five payout options compared — the Maximum Single Life Annuity, Option 1 (present-value death benefit), Option 2 (100% joint-and-survivor), Option 3 (50% joint-and-survivor), and Option 4 (lump-sum withdrawal of accumulated contributions and interest), with worked examples showing the monthly difference and what each provides your survivor
- Form PSRS-8 walkthrough — the documents to gather before you begin, what each section of the Application for Retirement asks for, how to enter your option election and beneficiary designation, and the common filing errors that cause PSERS to reject the form and delay your first check
- Act 5 hybrid class integration — for Class T-G and T-H members, how the defined contribution component administered by Voya Financial interfaces with your PSERS defined benefit annuity, and the dual-provider distribution process
- Health Options Program and Premium Assistance — eligibility for the $100/month reimbursement, HOP enrollment windows, Medicare Advantage and Supplement plan structures, and coordination with your district's bridge coverage
- Social Security after the WEP/GPO repeal — the Social Security Fairness Act signed January 5, 2025 repealed both provisions; the guide explains why standard PSERS members who pay FICA taxes were never affected, and what the repeal means for members with non-covered service from another state
- Post-retirement cash flow and re-employment — how to budget for the 60-to-90-day gap before your first PSERS payment, and the emergency and shortage rules governing return-to-service
- 8 fillable planning worksheets — payout option comparison, retirement countdown calendar, first-check cash flow planner, service credit audit, health benefit transition checklist, document preparation checklist, lump-sum tax decision worksheet, and agency communication log
Who This Is For
- Pennsylvania K-12 teachers, instructional specialists, and department chairs one to two years from their PSERS retirement date
- School administrators — principals, assistant superintendents, and business managers — preparing their Application for Retirement
- Non-certified school support staff — administrative assistants, custodians, cafeteria workers, transportation staff, and instructional aides — who need to understand the first-check delay and Premium Assistance eligibility
- Intermediate unit, career and technical center, charter school, and community college employees covered by PSERS
- Spouses involved in the payout-option decision who want to see the survivor trade-offs in plain language
- Members with prior divorces whose Domestic Relations Order may constrain their option election or beneficiary designation
Why Not the Free Handbook
The official PSERS handbooks are accurate. They are also written for every membership class at once, in statutory language that covers every edge case for every tier simultaneously. A Class T-D member reads superannuation rules that apply only to Class T-E. The exit counseling slides present Options 1 through 4 alongside the Maximum without explaining how to weigh them against your family's health situation or survivor needs. And the Member Self-Service portal shows estimate numbers without explaining the formula behind them.
The union's pre-retirement seminars give a broad overview in a group setting. Commercial financial advisers offer free workshops that end with a pitch to roll your 403(b) into their products — and some of them still warn that WEP will reduce your Social Security, eight months after Congress repealed it. The peer advice on Reddit and school-staff forums routinely conflates Class T-C rules with Class T-E rules and misinterprets Option 4's effect on the monthly check.
This guide puts the official rules in order — one path, one membership class at a time, from first estimate to first payment — without recommending an option, selling an annuity, or speaking for PSERS.
Full Refund, No Time Limit
If the guide does not help, email [email protected] for a full refund. No time limit, no form to fill out.
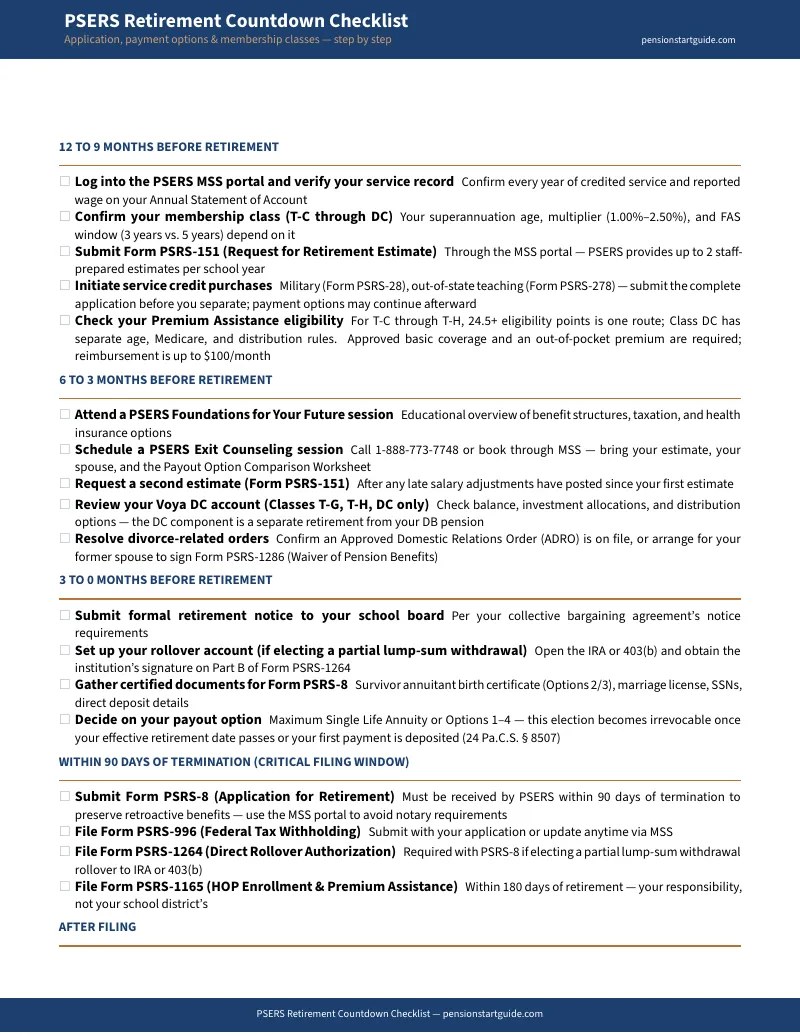
Get the Free Checklist or the Full Guide
Download the free PSERS Retirement Countdown Checklist to see every milestone from 12 months out to 90 days after retirement. When you're ready for the full filing sequence — membership class identification, all five payout options compared, the Form PSRS-8 walkthrough, Premium Assistance eligibility, and the service credit purchase deadline — get the complete guide for .