You Ran Your STRS Ohio Estimate — Now You're Staring at Six Payout Options and a PLOP Decision That's Permanent
STRS Ohio prints the numbers. It does not explain the trade-offs. Plan I gives you the highest monthly check — but if you die the day after your first payment, your spouse gets nothing beyond a refund of remaining contributions. Plan II Option 1 guarantees your spouse a lifetime pension at the same monthly amount — but that amount is permanently lower, even if your spouse predeceases you and you chose "Without Reversion." The Partial Lump-Sum Option Plan lets you take up to 36 months of your Single Life Annuity as cash — but every dollar permanently reduces your monthly check using age-based actuarial factors. The Online Personal Account shows the numbers side by side. Nobody puts them in order with worked examples that show what each option actually costs you per month for life.
Meanwhile, three plan tiers use the same 2.2% multiplier formula but different eligibility rules and distribution processes. A Defined Benefit member reading the Combined Plan brochure thinks the age-60 minimum applies to them. A Combined Plan member assumes they can annuitize their defined contribution balance and still leave a refund to beneficiaries — they can't. Confusing the two means planning around rules that don't apply to your plan.
The STRS Ohio Retirement Filing Sequence — Every Step, in Order, for Your Plan Tier
The STRS Ohio Retirement Guide is a step-by-step filing sequence that follows one member's path from the first benefit estimate through the first pension payment. It identifies your plan tier, walks through the Service Retirement Application, lays every Plan of Payment side by side with worked examples, explains the PLOP's permanent actuarial reduction at your exact age, and covers the spousal consent, health care, and reemployment decisions that have hard deadlines you cannot extend. It never recommends a plan — it explains what each one does, what it gives up, and what questions to bring to your STRS Ohio counselor.
What's Inside
- Your plan tier, identified — Defined Benefit, Combined Plan, and Defined Contribution, each tier's benefit formula (2.2% of your five highest years of Ohio public earnings times your years of service for DB and Combined Plan defined benefit portions), and the eligibility rules that apply to your tier alone
- Current board eligibility rules — the 32-year unreduced service requirement extended through May 1, 2035, the 27-year reduced option, age-based eligibility at 60 and 65, and how statutory grandfathering locks your eligibility once you meet the threshold even if the board raises requirements later
- Service credit audit and purchases — how to verify total qualifying credit across STRS, OPERS, and SERS, which types you can buy (military service, restored withdrawn service, leaves of absence), purchase deadlines, and the pre-tax 403(b)/457(b)/IRA rollover steps to pay STRS Ohio before your retirement date
- All Plans of Payment compared — Plan I (Single Life Annuity), Plan II Options 1 through 4 (Joint and Survivor with 100%, 50%, custom amount, and multiple beneficiaries), and Plan III (Annuity Certain with 5-, 10-, or 15-year guaranteed periods), with worked examples showing how each option changes your monthly check and what it provides your survivor
- With Reversion vs. Without Reversion — how choosing reversion under Plan II lets your benefit return to the unreduced Single Life rate if your beneficiary predeceases you or your marriage ends by court order, versus the permanent, irreversible election of Without Reversion — and why the choice between them changes depending on your beneficiary's age and health
- PLOP walkthrough with actuarial reduction tables — how taking 6 to 36 months of your Single Life Annuity as a lump sum permanently reduces your monthly pension, with worked reduction examples at ages 57, 60, and 65, the three disbursement choices (direct deposit with mandatory 20% federal withholding, direct rollover, or combination), and the 91-day wait before PLOP funds arrive
- Spousal consent and notarization — which elections trigger the consent requirement (Plan I, any PLOP, or a survivor benefit below 50%), what happens when consent is withheld (STRS defaults to Plan II with 50% survivor and zero PLOP), and how to complete the notarized signature
- STRS health care program — the 20-year service credit threshold for monthly premium subsidies (retirements on or after August 1, 2023), the Health Care Assistance Program for lower-income retirees with 25+ years of service, and the Medicare Part A and B enrollment timeline at age 65
- Social Security after the WEP/GPO repeal — the Social Security Fairness Act signed January 5, 2025 repealed both the Windfall Elimination Provision and the Government Pension Offset for benefits payable from January 2024; the guide explains how to file for unreduced private-sector Social Security or spousal benefits and claim retroactive back-pay
- Reemployment and forfeiture rules — the mandatory two-month waiting period, the one-day break in service requirement, and exactly how STRS calculates forfeiture using the full unreduced Single Life Annuity rate for every month worked during the waiting period
- Divorce and Division of Property Orders — how a DOPO divides your pension using a coverture fraction, the clerk-of-court transmission requirement, the 60-day STRS review period, and how a court order can force a Joint and Survivor election naming a former spouse
- 8 fillable planning worksheets — payout option comparison, retirement countdown calendar, first-check cash flow planner, service credit audit, PLOP tax decision worksheet, health benefit transition checklist, document preparation checklist, and agency communication log
Who This Is For
- Ohio K-12 public school teachers, department chairs, and instructional coaches one to two years from their STRS Ohio retirement date
- District and building administrators — superintendents, principals, and assistant principals — preparing their Service Retirement Application
- Higher education faculty at Ohio public universities and community colleges, including those with residual STRS Ohio balances alongside an Alternative Retirement Plan
- Combined Plan and Defined Contribution Plan members who need to navigate two separate distribution processes at retirement
- Spouses involved in the Plan of Payment decision who want to see the survivor trade-offs between Plan I, Plan II, and the PLOP in plain language before signing the notarized consent form
- Members with prior divorces whose Division of Property Order may constrain their payout election or beneficiary designation
Why Not the Free Handbook
The official STRS Ohio handbooks are accurate. They are also written for every plan tier at once, in system language that combines Defined Benefit, Combined Plan, and Defined Contribution rules in the same brochure. A DB member reads Combined Plan eligibility tables and thinks the age-60 minimum applies to them. The Plan of Payment brochure presents Plan I alongside Plan II and Plan III without explaining how to weigh the monthly reduction against your family's survivor needs, health situation, or existing life insurance. And the Online Personal Account displays estimate numbers without explaining the formula behind them or what happens to those numbers if you take a PLOP.
Financial advisers offer free "pension reviews" that end with a pitch to roll your PLOP into their products. Some still warn that the Windfall Elimination Provision will reduce your Social Security, nearly two years after Congress repealed it. The union's pre-retirement workshops give a broad overview in a group setting, focused more on board governance and COLA advocacy than the administrative steps of filing your application. The peer advice on Facebook groups and ORTA reform threads routinely confuses DB eligibility rules with Combined Plan rules and misinterprets how the PLOP actuarial factor works.
This guide puts the official rules in order — one path, one plan tier at a time, from first estimate to first payment — without recommending a plan, selling an annuity, or speaking for STRS Ohio.
Full Refund, No Time Limit
If the guide does not help, email [email protected] for a full refund. No time limit, no form to fill out.
Get the Free Checklist or the Full Guide
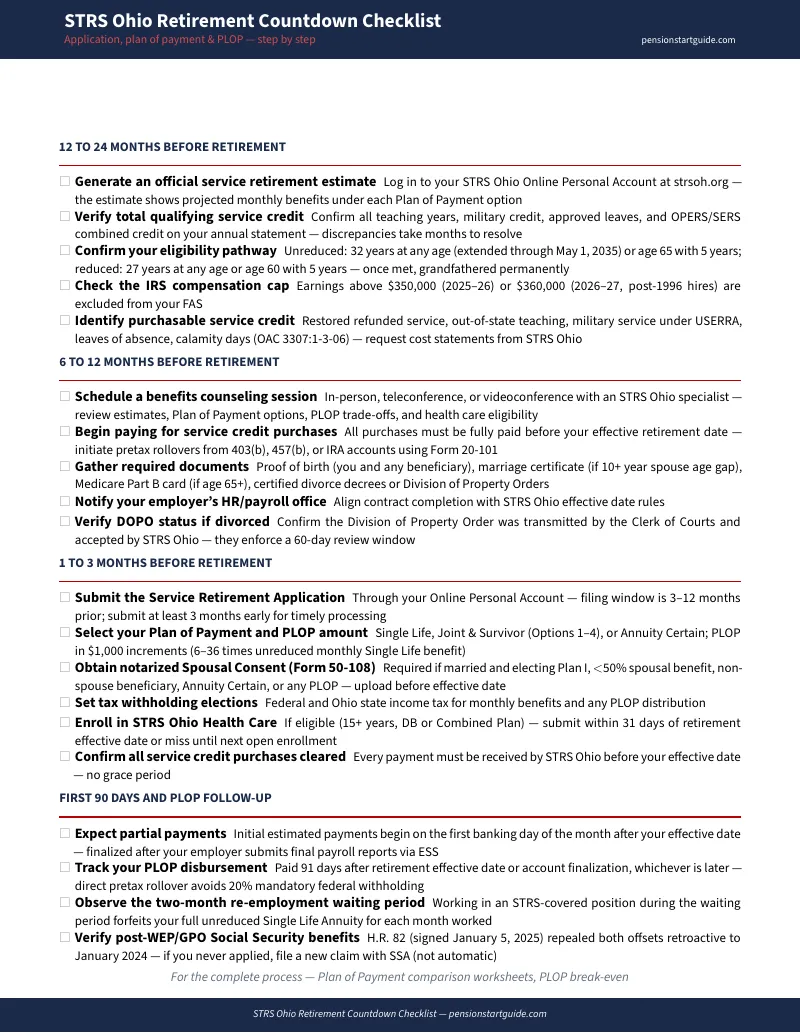
Download the free STRS Ohio Retirement Countdown Checklist to see every milestone from 12 months out to 90 days after retirement. When you're ready for the full filing sequence — plan tier identification, all Plans of Payment compared, the PLOP actuarial walkthrough, spousal consent requirements, and the service credit purchase deadline — get the complete guide for .