You get one shot at your OPERS plan of payment. The member handbook won't walk you through the trade-offs before you sign.
The moment OPERS issues your first benefit payment, the plan of payment you selected is locked. Single Life, Joint Life at 10%, 25%, 50%, 75%, or 100%, Multiple Life — whichever you choose follows you for the rest of your life. Ohio Revised Code Section 145.46 makes the election irrevocable, with only narrow exceptions for marriage, divorce, or the death of a designated survivor.
OPERS counselors explain the rules. They generate estimates. But they cannot sit with you at the kitchen table and walk through what each option actually means for your household — the monthly income trade-off against survivor protection, the PLOP lump sum against a permanently reduced check, the health care threshold you need to reach before your last day of service.
That gap between knowing the rules and understanding the trade-offs is where costly mistakes happen. A service credit purchase started too late to complete before the retirement date. A plan of payment elected without mapping the spousal consent requirements. A PLOP expected on day one of retirement that actually arrives 90 days after the first monthly check. A health care allowance that never materializes because qualifying service fell short of 20 years.
The OPERS Retirement Decision System
This is not a summary of the member handbook. The Ohio OPERS Retirement Guide is a structured decision system that puts your transition group's specific rules, deadlines, and trade-offs in the order you actually need them — from confirming your group under Senate Bill 343 to collecting your first payment and receiving your PLOP disbursement.
Every chapter follows the same pattern: what the rule is, what it means for your specific transition group (A, B, or C) and plan (Traditional, Member-Directed, or Combined), what the trade-offs look like in practice, and what questions to bring to your OPERS counselor. The guide never tells you which option to choose. It makes sure you understand exactly what each option does before you sign.
What's Inside
- Transition Group Verification Protocol — because getting your group wrong means every eligibility date, FAS window, and multiplier that follows is wrong. The guide maps your hire date, years of service as of January 7, 2013, and prior retirement eligibility to Group A, B, or C under Senate Bill 343, then shows you the specific 3-year or 5-year FAS window, benefit multiplier, and unreduced retirement threshold that apply to you.
- Plan of Payment Comparison Worksheet — not just definitions, but what each option actually costs you. Single Life pays the highest monthly amount but terminates all payments at death. Joint Life at 10%, 25%, 50%, 75%, or 100% protects your survivor but permanently reduces your check by an actuarially calculated amount based on both your ages. Multiple Life extends that protection to two, three, or four beneficiaries. Print the worksheet and compare with real numbers from your OPERS estimate.
- PLOP Decision Worksheet — the Partial Lump-Sum Option Payment lets you take 6 to 36 months of your Single Life benefit as a lump sum, but your monthly pension is actuarially reduced for life. The worksheet records the multiplier, the permanent monthly reduction, the COLA dollar loss, the 90-day post-first-check disbursement hold that catches unprepared retirees, and the direct IRA or 457(b) rollover versus cash distribution (20% federal withholding on cash).
- CBBC Anti-Spiking Worksheet — if your salary increased substantially in your final years, the Contribution-Based Benefit Cap under ORC 145.333 may cap your pension below the standard calculation. The worksheet logs your FAS-window salaries and the Group A 5% cap check, then records the official OPERS counselor estimate.
- Service Credit Audit Checklist — military service, restored (refunded) contributions, authorized leave, non-contributing Ohio public service. The printable checklist records estimated cost, payment method, and paid-in-full date so every purchase clears before the hard cutoff at your effective retirement date. Once you retire, unpurchased service credit is gone.
- Health Care Eligibility Tracker — since 2022 OPERS uses a Health Reimbursement Arrangement model, not a self-insured plan. Pre-Medicare retirees receive a monthly HRA deposit; Medicare-eligible retirees transition to the Via Benefits Medicare Connector. The tracker checks group-specific thresholds (including the 20-year qualifying health credit for Medicare-age retirees), records your allowance, and maps Form HC-1G and Connector enrollment.
- Spousal Consent & DPO Compliance — if you elect Single Life as a married member, Ohio law requires notarized spousal consent. If a Division of Property Order from a prior divorce is on file with OPERS, it may restrict your plan of payment choices or lump-sum distributions. The guide covers the legal requirements for both situations.
- Law Enforcement & Public Safety Supplement — specialized age and service tables, the service conversion formula for members who transferred between divisions, and the CBBC rules specific to law enforcement and public safety officers.
- Social Security Integration After WEP/GPO Repeal — the Social Security Fairness Act signed January 5, 2025 repealed both the Windfall Elimination Provision and the Government Pension Offset for benefits payable from January 2024. The guide explains step-by-step SSA filing instructions for OPERS members who never applied because of the old offsets, and how to secure retroactive adjustments dating back to January 2024.
- Retirement Timeline Planner — a T-12-month to T+90-day countdown covering benefit estimates, service credit purchases, employer Form SR-2 sign-off, Form SR-1 filing, the income gap before your first check, and the 90-day PLOP hold. An Agency Communication Log records every OPERS, HR, SSA, and Via Benefits contact.
Who This Is For
Ohio state, county, city, and township employees who are one to two years from submitting their OPERS retirement application. Law enforcement officers and public safety personnel navigating the specialized division tables. Spouses who need to understand the plan of payment trade-off together. Adult children helping a parent navigate the OPERS process.
This guide covers all three transition groups (A, B, and C), all three plan types (Traditional Pension, Member-Directed, and Combined), and both regular and law enforcement/public safety divisions.
Why Not Just Read the OPERS Handbook?
The OPERS member handbook is written for every member at once — Group A, Group B, Group C, Traditional, Combined, Member-Directed, regular employees, and law enforcement all sharing the same document. It defines every rule but does not put your specific steps in order or walk through the trade-offs between plan of payment options.
OPERS counselors are knowledgeable and helpful, but they are legally restricted from advising you on which option to choose or comparing the financial implications for your household. Financial advisers who specialize in public employee retirement charge $1,500 to $5,000+ for a planning engagement — and many still publish stale information about WEP and GPO as though the offsets are still in effect.
The guide fills the gap between the handbook and the adviser. It organizes the rules by the decisions you actually need to make, in the order you need to make them, with the trade-offs laid out so you can have an informed conversation with your counselor — or with your spouse — before you sign anything irrevocable.
Satisfaction Guarantee
Full refund, no time limit. If the guide does not help you navigate your OPERS retirement process, email [email protected] and we will refund your purchase.
Start With the Free Checklist — Then Decide
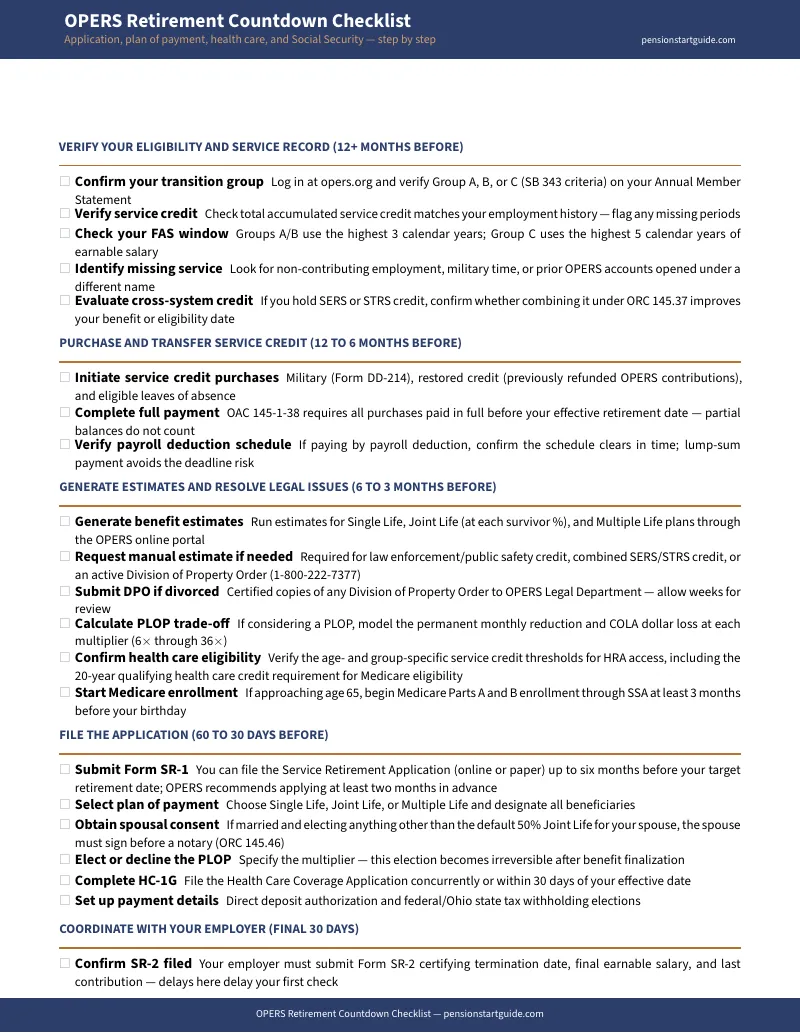
Download the OPERS Retirement Countdown Checklist for a 12-month timeline of 25 milestones, deadlines, and documents. It covers what to do and when. The full guide covers how — with the Plan of Payment Comparison Worksheet, PLOP Decision Worksheet, Service Credit Audit Checklist, CBBC Anti-Spiking Worksheet, Health Care Eligibility Tracker, Retirement Timeline Planner, and Agency Communication Log that turn each milestone into a completed step.
The checklist is free. The full guide is available when you are ready to go deeper. Either way, you walk away knowing more about your OPERS retirement than you did five minutes ago.