You get one shot at your MPSERS pension option. The ORS handbook won't walk you through the trade-offs before you sign.
The moment your retirement effective date arrives, the pension option you selected is permanent. Straight Life, 100% Survivor, 75% Survivor, 50% Survivor, or Equated Plan — whichever you choose follows you for the rest of your life. Under Michigan law, a married member who elects anything other than 100% Survivor must present a notarized spousal waiver on Form R0869C. Miss that step and ORS sends your application back.
ORS counselors explain the rules. They run pension estimates in miAccount. But they cannot sit with you at the kitchen table and walk through what each option actually means for your household — the monthly income trade-off against lifetime survivor protection, the Equated Plan's higher check before 62 against its permanent reduction after, the Premium Subsidy you might qualify for against the Personal Healthcare Fund that locks you out of the state health plan entirely.
That gap between knowing the rules and understanding the trade-offs is where costly mistakes happen. A spousal waiver executed without a notary. A health insurance enrollment submitted on day 31, triggering a six-month coverage gap. A service credit purchase started too late to complete before the last day of active employment. A 2012 PA 300 election that changed your pension multiplier from 1.5% to 1.25% — and you never verified which one you chose.
The MPSERS Retirement Decision System
This is not a summary of the member handbook. The Michigan MPSERS Retirement Guide is a structured decision system that puts your plan tier's specific rules, deadlines, and trade-offs in the order you actually need them — from confirming your tier and PA 300 elections to collecting your first pension payment on the 25th of the month.
Every chapter follows the same pattern: what the rule is, what it means for your specific plan tier (Basic, MIP, Pension Plus, or Pension Plus 2), what the trade-offs look like in practice, and what questions to bring to your ORS retirement counselor. The guide never tells you which option to choose. It makes sure you understand exactly what each option does before you sign.
What's Inside
- Plan Tier & PA 300 Election Verification — a fillable worksheet that maps your hire date, 2012 reform elections, and miAccount summary to the correct tier — Basic, MIP Fixed, MIP Graded, MIP Plus, Pension Plus, or Pension Plus 2 — then records the 36-month or 60-month FAC window, 1.5% or 1.25% multiplier, and unreduced eligibility threshold that apply to you.
- Final Average Compensation Worksheet — not just the formula, but which compensation items actually count. Reportable wages versus non-reportable lump-sum payouts, the 36-month versus 60-month averaging window by tier, and a printable salary log to verify your FAC before submitting the retirement application. One school administrator's longevity bonus counts toward FAC; another's performance incentive may not.
- Payout Option Comparison Worksheet — Straight Life pays the highest monthly amount but ends all payments and health coverage at your death. The 100%, 75%, and 50% Survivor Options protect your named beneficiary at the cost of a permanent actuarial reduction to your check. The Equated Plan pays more before age 62, then drops permanently — whether or not you actually file for Social Security at 62. Copy your miAccount estimates onto the worksheet, then work through the household-impact table with your spouse before anyone signs.
- Spousal Waiver Protocol — step-by-step walkthrough of Form R0869C, when a notarized spousal signature is legally required, what happens if the spouse refuses, and how an Eligible Domestic Relations Order from a prior divorce can restrict your benefit distribution or redirect a portion of your pension to a former spouse.
- Service Credit & TDP Payoff Checklist — military service, refunded contributions, universal buy-in. The printable checklist records estimated cost, Tax-Deferred Payment payoff status, and paid-in-full date so every purchase clears before the hard cutoff at your last day of active employment. Once you retire, unpurchased service credit is gone.
- Healthcare Decision Worksheet — record your Premium Subsidy percentage (30% at 10 years of service up to 80% at 23) or Personal Healthcare Fund status, compare plan premiums side by side, and track the 30-day enrollment window. PHF holders pay 100% of the premium and receive a 2% employer match through Voya; electing PHF means no state health plan in retirement — ever. Medicare Part A and Part B integration at age 65 is on the same sheet.
- Return-to-Work Rules Under PA 147 — the current provisions through October 2028: a bona fide separation, the $15,100 calendar-year earnings limit, the six-month break-in-service alternative, and what happens to your pension and retiree health benefits if you come back to a Michigan public school reporting unit.
- Social Security After the WEP/GPO Repeal — the Social Security Fairness Act, signed January 5, 2025, repealed both the Windfall Elimination Provision and the Government Pension Offset for benefits payable from January 2024 onward. Michigan educators pay Social Security taxes on their public school wages, so WEP rarely affected standard MPSERS pensions. The guide explains who was actually affected, how to verify your retroactive SSA adjustment, and how to file a new claim if you never applied because of the old offsets.
- PA 4 Pension Tax Phase-In — the Michigan income tax treatment of pension income under PA 4 of 2023, the phase-out schedule through 2026, and what the transition means for your take-home pension in the first years of retirement.
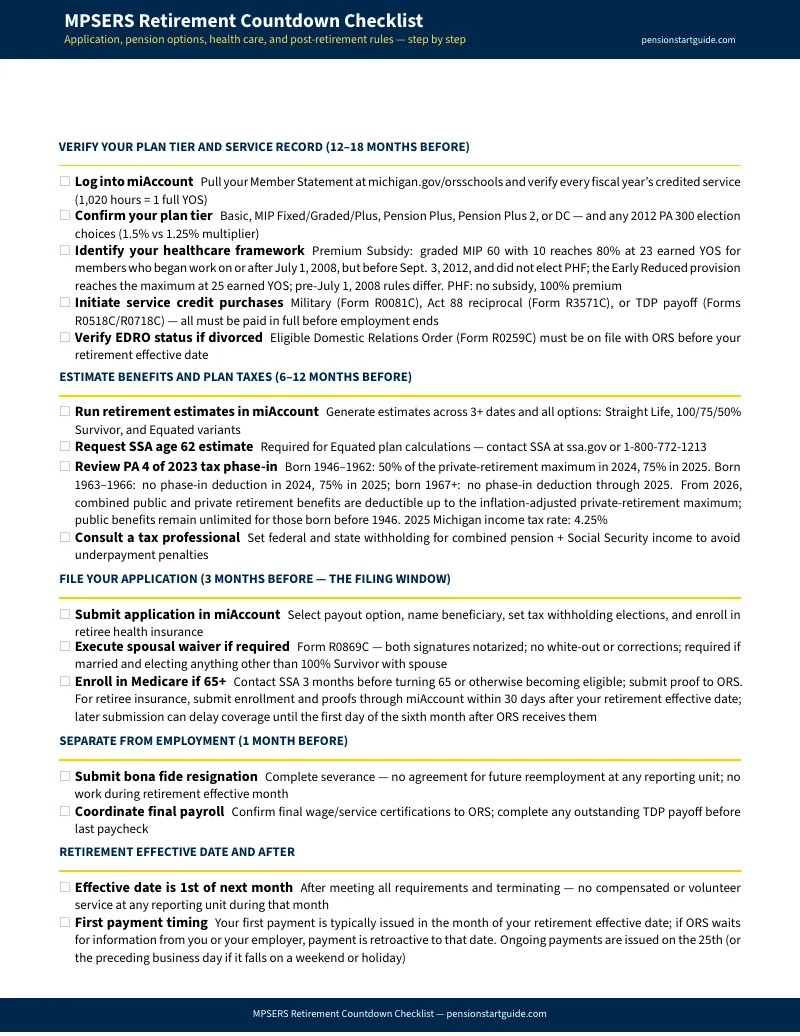
- Retirement Countdown Timeline — an 18-month fillable countdown covering miAccount estimate runs, service credit purchases, the three-month advance filing requirement, health insurance enrollment, and the first pension payment. Ongoing payments issue on the 25th; a delayed first payment is retroactive to the effective date.
- Pre-Application Document Checklist — birth certificates, marriage license, DD-214, EDRO, Form R0869C, Medicare proof, and the rest of the packet ORS expects before you submit in miAccount.
- Agency Communication Log — date, person, outcome, and follow-up for every ORS, district HR, SSA, and Voya contact.
Who This Is For
Michigan K-12 teachers, school administrators, and support staff who are one to two years from submitting their MPSERS retirement application through miAccount. Community college and university employees with MPSERS coverage navigating the intersection of their pension and separate 403(b) or 457 accounts. Members who elected DC conversion under 2012 PA 300 and need to coordinate a frozen DB pension with their defined contribution drawdown. Married members and their spouses working through the pension option decision together — especially when one partner wants the maximum monthly check and the other wants lifetime survivor protection.
The guide covers all five plan tiers (Basic, MIP, Pension Plus, Pension Plus 2, and DC Converted), all PA 300 election outcomes, and both the Premium Subsidy and Personal Healthcare Fund healthcare frameworks.
Why Not Just Read the ORS Handbook?
The ORS member handbook covers every plan tier in a single publication — Basic, MIP Fixed, MIP Graded, MIP Plus, Pension Plus, Pension Plus 2, DC Converted — all sharing the same pages. It defines every rule but does not separate your tier's specific steps from the tiers that do not apply to you. The result is information overload at the moment you can least afford confusion.
Financial advisers who work with Michigan educators often use MPSERS planning as a lead generation channel for 403(b) rollover management or annuity sales. Many continue to publish warnings about WEP and GPO pension reductions even though both provisions were repealed in January 2025. An adviser engagement runs $1,500 to $5,000+, and the regulatory content may already be stale.
The guide fills the gap between the handbook and the adviser. It organizes the rules by the decisions you actually need to make, in the order you need to make them, with the trade-offs laid out so you can have an informed conversation with your ORS counselor — or with your spouse — before you sign anything irrevocable.
Satisfaction Guarantee
Full refund, no time limit. If the guide does not help you navigate your MPSERS retirement process, email [email protected] and we will refund your purchase.
Start With the Free Checklist — Then Decide
Download the MPSERS Retirement Countdown Checklist for an 18-month timeline of milestones, deadlines, and documents. It covers what to do and when. The full guide covers how — with the Plan Tier Verification, FAC Worksheet, Payout Option Comparison Worksheet, Spousal Waiver Protocol, Service Credit Audit Checklist, TDP Payoff Checklist, Healthcare Decision Worksheet, Pre-Application Document Checklist, Agency Communication Log, and Retirement Countdown Timeline that turn each milestone into a completed step.
The checklist is free. The full guide is available when you are ready to go deeper. Either way, you walk away knowing more about your MPSERS retirement than you did five minutes ago.