You've Earned the Pension. Now You Need the Playbook to Claim It Right.
You've spent 25 or 30 years in California classrooms. You've earned a CalSTRS pension that will pay you for the rest of your life. But between the benefit estimate, the age factor tables, the payout option election, the spousal signature, the DBS distribution, and the health insurance gap — the actual process of retiring feels like a second full-time job.
And the stakes are permanent. Once CalSTRS issues your first payment and 30 days pass, your payout option is locked for life. Choose the wrong one, miss a deadline, or file with an uncredited year of service — and there is no undo.
The CalSTRS Retirement Execution System puts the entire application process in the order you actually face it, from running your first serious benefit estimate to tracking your first direct deposit. No financial advice. No option recommendations. Just the formulas, the forms, the deadlines, and the trade-offs — explained clearly enough that you walk into your CalSTRS counselor appointment with better questions, not more confusion.
What's Inside the Guide
- Benefit formula decoded for your tier — whether you're 2% at 60 or 2% at 62 (PEPRA), the guide walks through exactly how service credit, age factor, and final compensation combine, with worked dollar examples for both tiers so you can see what each variable actually does to your monthly check
- Age factor timing worksheets — quarter-year increment tables showing what retiring at 60 vs. 60.5 vs. 61 actually costs or gains, so you can pick a retirement date with numbers instead of guesswork
- Payout option comparison — the Member-Only Benefit, all three Joint-and-Survivor percentages, the Compound Option for complex families, and the Pop-Up Provision that most members don't know exists — laid out side by side with the trade-off each one makes between your monthly income and your survivor's long-term protection
- Spousal consent walkthrough — what Education Code § 22453 requires, how to handle a reluctant signature, what happens with a divorce or QDRO on file, and how to get a court-ordered waiver when consent is impossible
- DBS distribution decision — lump sum, monthly annuity, or rollover into a 403(b)/457/IRA, with the tax implications of each choice and the timing relative to your primary pension check
- Service credit purchase deadline — redeposits, out-of-state teaching, military service, and maternity leave buybacks all have one hard rule: they must be paid or under a binding installment contract before your retirement date, not after
- Health coverage bridge — the exact month your district insurance terminates, how COBRA bridges the gap, the Medicare Part A and Part B enrollment windows, and the MPPP eligibility rules that depend on whether your district participated in a Medicare Division
- Social Security after the repeal — the Social Security Fairness Act eliminated WEP and GPO for benefits payable from January 2024. If you worked outside education or have a spouse's Social Security record, the old reductions no longer apply. The guide covers how to file the retroactive claim
- First payment tracker — the 45-day processing target, how interim checks work at 80–85% of your estimated benefit, the true-up lump sum once your district's payroll audit clears, and what to do if your check is late
Who This Is For
- California K–12 teachers, specialists, and counselors within one to two years of retirement
- Community college faculty — including adjuncts tracking service credit across multiple districts
- Certificated administrators managing PEPRA compensation caps and large DBS balances
- Spouses and domestic partners who need to understand what they're signing — and what each option means for their income if the member dies first
Why Free Online Sources Leave You Guessing
The CalSTRS Member Handbook is 200+ pages covering every member class at once — active, disabled, deceased, classic, PEPRA, Cash Balance Benefit. It's legally thorough and practically overwhelming. You read it looking for your next step and come out with fifteen new questions.
Union pre-retirement seminars cover the basics in 90 minutes and can't get into your specific tier's age factor table or walk through the DBS tax decision. Financial advisors offering "free CalSTRS pension reviews" are selling rollover products and annuities — their content exists to capture leads, not to give you a neutral process.
And over 70% of non-official websites still describe the Windfall Elimination Provision and Government Pension Offset as active law — both were repealed in January 2025. If you're reading content that says your CalSTRS pension will reduce your Social Security spousal benefit by two-thirds, that content is wrong.
This guide follows one process — your service retirement application — in the order you actually face it. It's updated for the 2025 Social Security Fairness Act. It explains the trade-offs without telling you which option to pick. And it's built so you can work through it with a pencil and come out knowing exactly what to file, when to file it, and what each election means for your household.
Satisfaction Guarantee
If the guide doesn't deliver what you expected, email [email protected] for a full refund, no time limit. We read every message.
Start With the Free Checklist — or Get the Full Guide
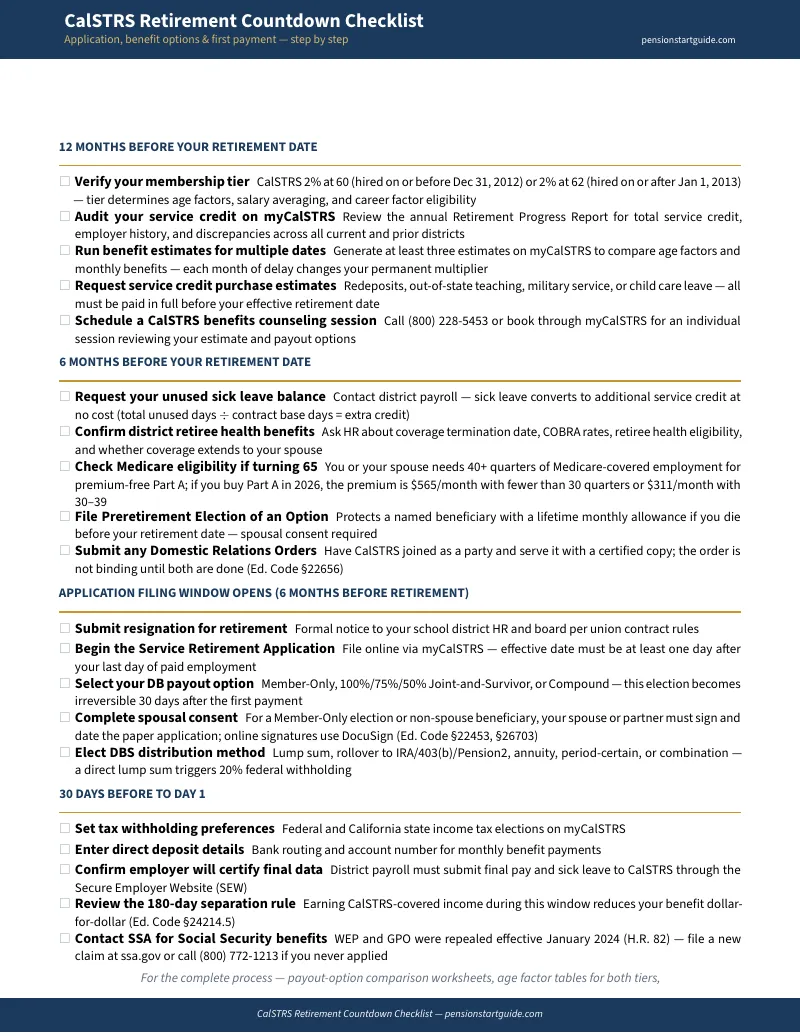
Download the CalSTRS Retirement Countdown Checklist for a month-by-month timeline of what to do at 12 months, 6 months, 120 days, and 30 days before your retirement date. It's free, and it's the same checklist included in the full guide.
When you're ready for the formulas, the payout comparison worksheets, the spousal consent walkthrough, and the complete application-to-first-payment sequence, the full CalSTRS Service Retirement Guide is available for .